Can You Handle a 25% Drop in Your 401(k)?
MarketDash Editorial Team
Author
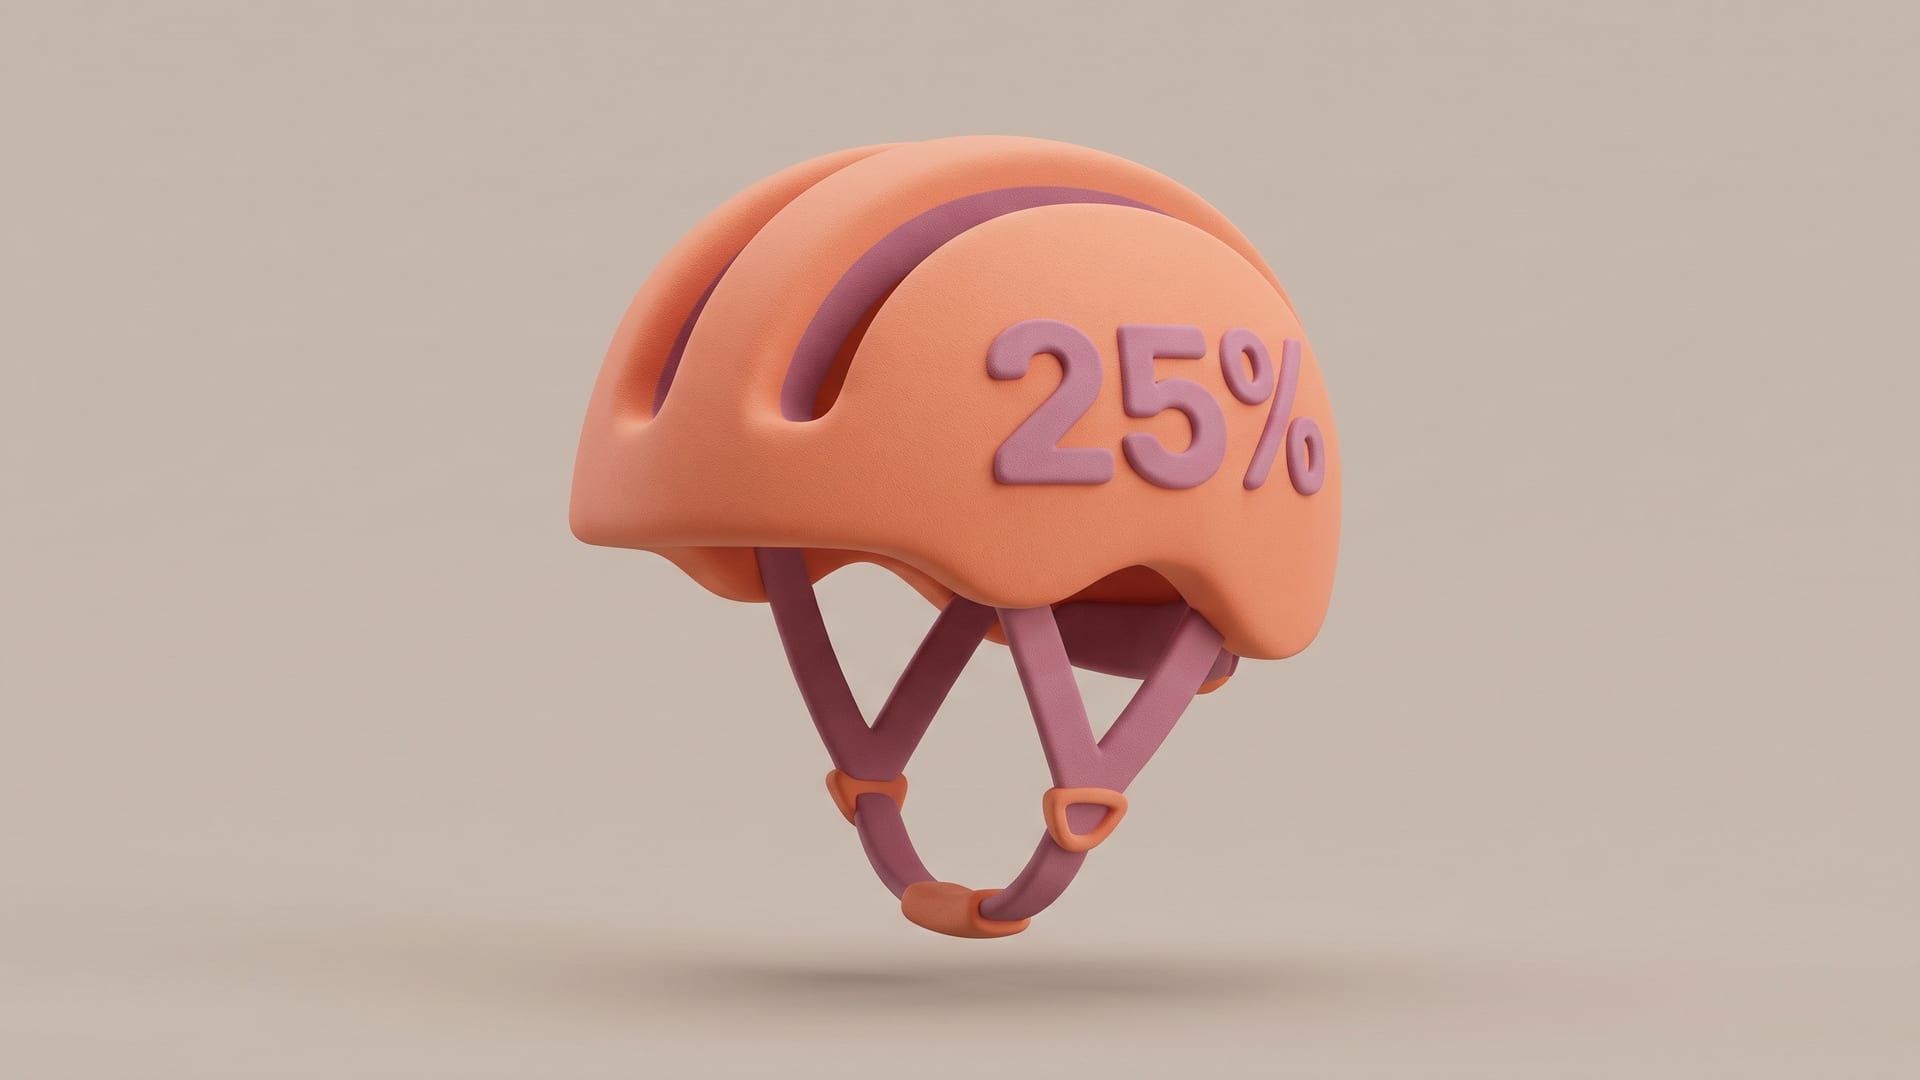
From 2016 through 2025, the S&P 500 finished higher in 8 of its 10 calendar years, with an average yearly return of +13.9%, not counting dividends (the cash payouts companies send shareholders). Over those same ten years it also fell 34.1%, 25.4%, and 20.2% from a high. Both sentences describe the same market. You do not get to accept one and decline the other.
Here is the part that costs people the most money. The largest of those three drops, 34.1%, happened in 2020, which finished the year up 16.2%. The fall was real. So was the year. Anyone who sold in the middle because the drop felt like the start of something worse collected the loss and handed back the gain. The long-run average is not a smooth ride with the bumps airbrushed out. It is what is left after the bumps.
The drops all ended. The schedule did not.
Three declines, three different moods:
- 34.1%, from Feb 19, 2020 to Mar 23, 2020. Thirty-three days of falling. Back to the old high 148 days after the bottom.
- 25.4%, from Jan 3, 2022 to Oct 12, 2022. Two hundred and eighty-two days of falling, which is enough time to build an entire personality around being miserable. Back to the old high 464 days after the bottom.
- 20.2%, from Sep 20, 2018 to Dec 24, 2018. Ninety-five days of falling. Back to the old high 126 days after the bottom.
Every one of those ended, and every one clawed back to its old high. That is the reassuring half. The other half: recovery took 126 days in one case and 464 in another, and nobody standing inside a decline knows which one they have been handed. "Wait for the bottom, then get back in" sounds disciplined. In practice it means being right twice, and the second guess has to happen while your stomach is still somewhere near your shoes.
The flinch test
Open your brokerage app and find the total you hold in stock funds. Now imagine that number about a quarter smaller, close to the S&P 500's 25.4% slide from its January 3, 2022 high to its October 12, 2022 low. How does that feel? If the honest answer is "I would sell," you just learned something genuinely useful, and it is not that the market is dangerous. It is that your stock allocation, meaning how you split your money between stocks and safer things like cash or bonds, is bigger than your tolerance.
Notice what a decline actually is: a price change. It becomes a loss the moment you sell. Until then it is a number on a screen moving around while the businesses underneath keep collecting revenue. Selling does two things. It turns a temporary markdown into a permanent one, and it makes you a market timer, meaning someone guessing when to be in and when to be out. That job has no training program and a brutal pass rate.
So fix it in the calm. If a one-quarter drop would rattle you, move some of that stock into cash or bonds now, while the headlines are boring. Yes, you give up some of that +13.9% average. That is the price of being able to stay invested at all, and it is cheaper than discovering your true risk tolerance at the worst possible moment.
The number you can actually control
While you are resizing, look at what you pay to invest. Start with $10,000 and add $500 a month for 20 years at 8% a year, before taxes and fees. With a 0.05% yearly fee you end near $341,000. With a 1% yearly fee you end near $301,000. The difference is about $41,000, a steep price for the privilege of receiving a statement.
For context on where the growth comes from: in the version with no fee at all, you put in about $130,000 over those 20 years and end with about $344,000. The growth on top is about $214,000. Fees get charged on the whole pile, growth included.
You cannot vote on the next 20% decline. You can vote on your allocation and on your fee, and both votes count.
Check it yourself in MarketDash
Open the Seasonality section on any stock you own and look at how often each month finished down. In the S&P 500's 2016 to 2025 history, September averaged -1.6% and was up in only 5 of 10 years, while November averaged +4.3% and was up in 9 of 10. A red month is furniture, not a fire alarm. If seeing one makes your thumb hover over the sell button, the fix is a smaller stock position, not a friendlier month. And when a drop makes you wonder whether the business itself changed, the Stock page's Intrinsic Value section shows the discounted cash flow and similar-companies estimates behind that number. Prices wobble. That estimate is what to check before you do anything.
Get Market News Alerts
Real-time alerts on price moves, news, and trading opportunities.
Join 20,000+ investors. No spam, ever.
Featured Articles
View all news
Nvidia Plunges 14% on Jensen Huang's Shock Exit, But Nasdaq 100 Shrugs It Off
Trump Picks Tim Cook to Replace Jensen Huang at Nvidia: 'A Legend Replaces a Legend'
Nvidia CEO Jensen Huang Resigns After 33 Years, CFO Colette Kress Takes Over As Interim CEO
Wall Street Takes A Chainsaw To Nvidia Price Targets: One Bank Slashes $465 To $186
Tesla's Best 5-Day Rally in Over a Year: Musk Pushes SpaceX Merger by December
Qualcomm Stock Jumps as Wall Street Rotates Out of Nvidia After Huang's Shocking Exit
Bitcoin Slips Below $72,000: Schwab Strategist Points To 'Known Unknowns'